How to Check Which CAM Expenses Were Grossed Up in Excel
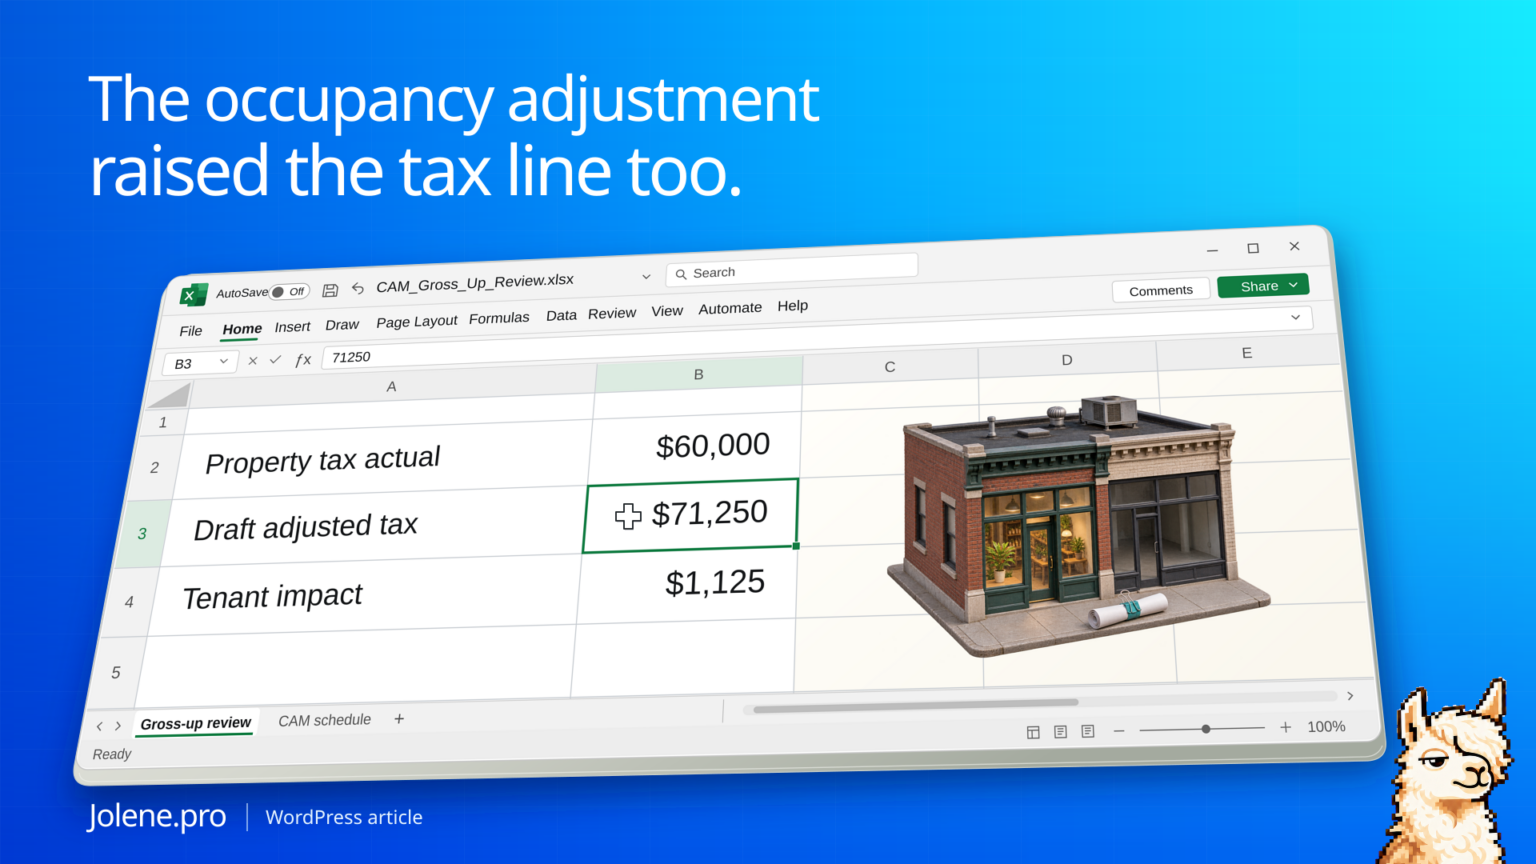
The property was 80% occupied and the CAM workbook adjusted expenses to a 95% basis. The janitorial line moved, as expected under the sample lease. The tax line moved too. The accountant needs to see every adjusted expense before issuing the reconciliation.
Use the approved lease’s eligible expense rules and occupancy basis. Apply the approved gross-up method only to eligible lines and compare the result with the amounts already in the statement.
One variable line and one fixed line
For this simplified example, the lease permits linear adjustment of variable janitorial expense from 80% to 95% occupancy and excludes fixed property taxes from gross-up.
| Expense | Actual | Adjusted in draft | Lease-based amount |
|---|---|---|---|
| Variable janitorial | $40,000 | $47,500 | $47,500 |
| Fixed property tax | $60,000 | $71,250 | $60,000 |
| Total | $100,000 | $118,750 | $107,500 |
The draft is $11,250 high at the pool level. At a 10% share in this sample, the difference is $1,125 before estimated payments or any other lease adjustments.
Record the rules with the expense mapping
Set up the property, recovery pool, actual and target occupancy, eligible accounts, and approved calculation. For mixed costs, keep fixed and variable components separate where the approved method calls for it. The source of the occupancy basis matters as much as its number.
Audit every adjustment
Keep booked and adjusted amounts side by side. For the sample eligible line, use actual variable expense divided by actual occupancy, multiplied by target occupancy. Use your approved method in practice. Surface zero occupancy, missing eligibility and timing differences for review.
Find the adjusted rows that need a second look
Bring the expense detail, draft statement, and approved lease inputs together. Keep any cap interactions explicit in the workbook.
Which expense lines were grossed up contrary to the approved rules? Show original and adjusted amounts, the occupancy basis, impact by tenant and source rows.
Resolve the expense mapping with the property accountant before changing the statement.
ABA overview of operating expenses in commercial leases · Holland & Hart on gross-up provisions
The figures and identifiers in this example are synthetic. The displayed arithmetic was checked independently. A live Jolene.pro result could not be verified. Use the actual lease and approved accounting treatment before issuing a reconciliation.
Try this with your own spreadsheet at Jolene.pro. Follow Jolene.pro on LinkedIn for more spreadsheet guides.
For more checked examples, see Jolene.pro Workbook Studies.